
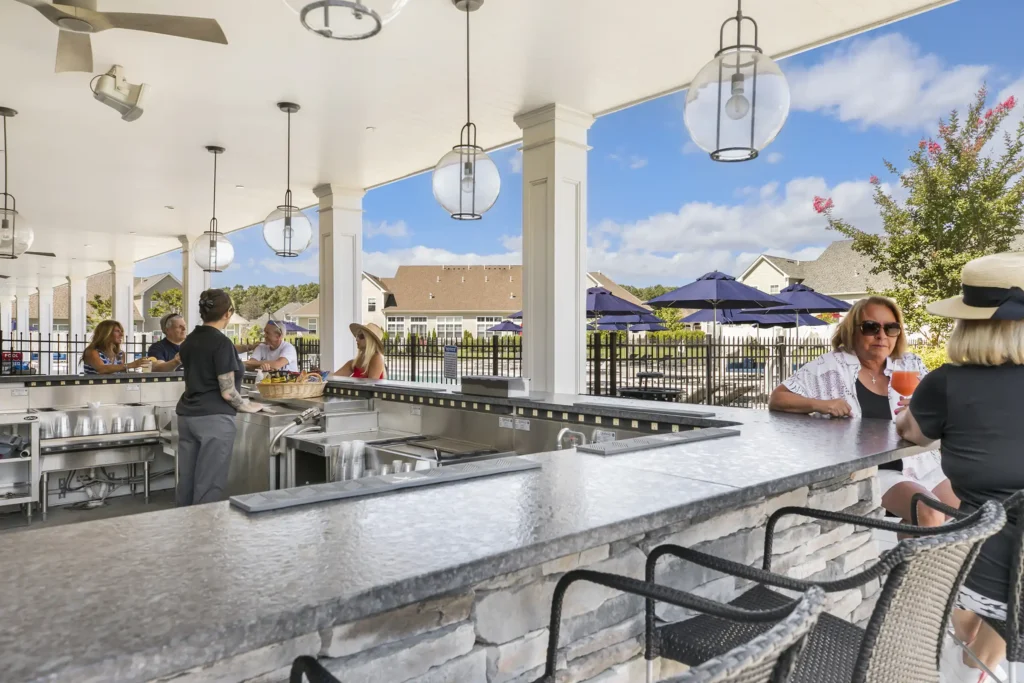
If you’re over 55 and questioning whether your current home still makes sense, you’re not alone. Many Long Islanders at this stage are weighing the same options: stay put, pursue downsizing after retirement into something smaller, or move into a lifestyle-first 55+ community. The decision isn’t purely financial. It involves where you want to spend the next chapter of your life, what you’re willing to trade off, and a realistic look at what the Long Island housing market looks like right now.
Key takeaways
- Downsizing after 55 is often about “rightsizing”: finding a home that fits your life now, not the one you built decades ago.
- The financial picture is more complex than it looks; transaction costs, capital gains exposure, and escalating HOA fees can significantly affect your net outcome.
- Upgrading into a 55+ community isn’t always cheaper than staying put, but it offers predictable expenses and lifestyle benefits that have real value.
What “downsizing” actually means after 55
The term gets thrown around a lot, but for many people over 55, downsizing a house for retirement isn’t about going smaller for its own sake. It’s about finding a home that fits your current life rather than the one you were living 20 or 30 years ago. Common motivations include reducing property taxes, trimming maintenance costs, and freeing up equity built over years of homeownership. Selling a long-held Long Island home can release substantial capital useful for retirement income or simply reduce financial pressure on a fixed income.
There’s also a physical dimension that doesn’t come up enough. A lot of older Long Island homes simply weren’t designed with aging in mind. Multiple floors, narrow doorways, no first-floor bedroom: these features that didn’t matter at 40 can become real concerns at 65 or 70. Moving into a ranch-style or single-level home, or one with walk-in showers and grab bars, isn’t a compromise. It’s a practical choice that supports safety and independence for the long term. One important financial note before listing: capital gains taxes apply if your profit exceeds $250,000 as an individual or $500,000 as a couple, so it’s worth sitting down with a financial advisor before putting a sign in the yard.
What “upgrading” looks like in this life stage
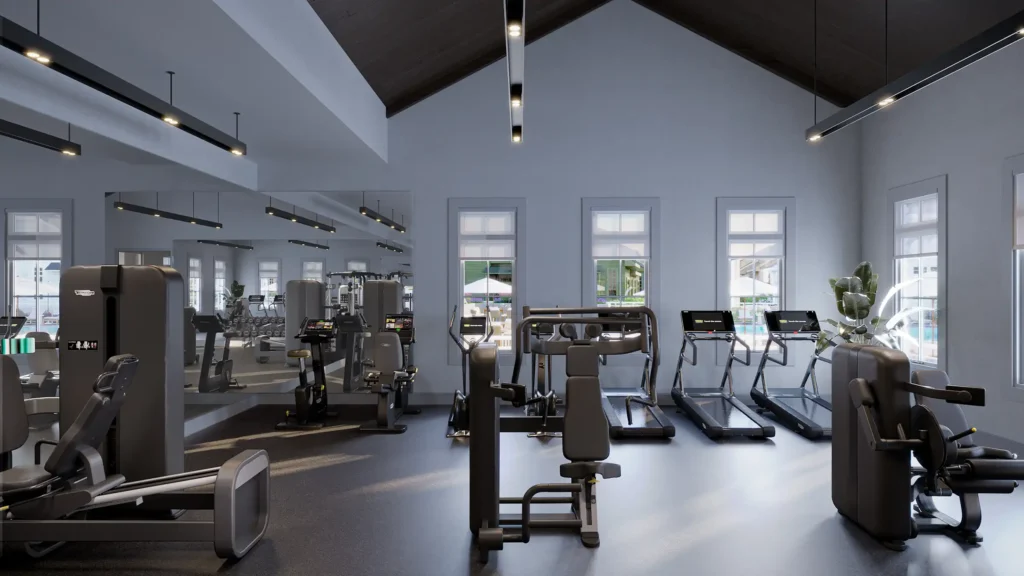
For a lot of 55+ buyers, an upgrade has nothing to do with more space. It means trading the to-do list of homeownership for a lifestyle that’s been thoughtfully designed for this stage of life. Instead of paying separately for a gym, a lawn service, and a social calendar, many 55+ communities bundle those things into a single monthly fee that covers amenities, maintenance, and community programming. The result is less friction, more time, and a built-in social environment designed specifically for people in the same life stage.
These communities offer things traditional neighborhoods don’t: structured social activities like yoga, tennis, and pickleball; gated access and on-site security; and shared spaces built for active adults. The trade-off is the monthly HOA fee, which varies widely and can be substantial, though it typically covers landscaping, exterior maintenance, and shared amenities, making monthly budgeting more predictable. At the higher end, some continuing care retirement communities carry significant entry costs on top of monthly fees, making them a major financial commitment worth analyzing carefully.
The real financial picture: Costs people often overlook
1. Transaction costs add up fast
Selling a home involves broker commissions, attorney fees, transfer taxes, and potentially capital gains taxes, all of which can take a meaningful bite out of your net proceeds. In some cases, staying in a paid-off home is cheaper than moving into a condo with high monthly fees once you factor everything in.
2. The “lock-in” effect is real on Long Island
Many homeowners who locked in low mortgage rates in previous years are hesitant to sell, because buying something new could mean taking on a significantly higher rate. Long Island home prices have continued to climb, making the financial calculus of moving more complex than it was even a few years ago.
3. HOA and condo fees can escalate
Monthly fees in 55+ communities are not fixed. They can increase with inflation, rising maintenance costs, or community upgrades. Anyone budgeting for a purchase should ask about fee history over the past 10 years, not just the current rate.
4. Aging in place has costs too
Retrofitting a current home with accessibility features like grab bars, walk-in showers, and widened doorways costs real money, but may still be more affordable than relocating. This path works best for people who are otherwise happy with where they live and don’t need the social or lifestyle benefits of a 55+ community.
How to decide: A practical framework
There’s no single right answer to when to downsize your home, or whether to downsize at all. The best decisions come from people who’ve been honest about what they want, done the math carefully, and given themselves time to process a significant life transition.
- Clarify your primary goal first
- Financial relief: lower taxes, freed equity, reduced maintenance costs
- Lifestyle upgrade: community, amenities, social connection
- Safety and accessibility: single-level living, proximity to healthcare
- Proximity to family or preferred locations on Long Island
- Run the real numbers, not just the sale price
- Compare total costs of selling and buying versus retrofitting your current home
- Include HOA fees, property tax changes, moving expenses, and capital gains exposure
- Take the emotional component seriously
- Leaving a long-time family home is a significant life transition, not just a financial one
- Work with professionals who know this market
- A Seniors Real Estate Specialist (SRES) is trained specifically for this type of transaction on Long Island
- Visit communities multiple times before deciding
- Talk to current residents about fee increases, maintenance response times, and community culture
- Treat it like a college search: what looks good on paper may not feel right in person
Finding the right fit on Long Island
Long Island offers a genuinely diverse range of options for 55+ buyers, from inland communities with easy LIE access to coastal enclaves along the South Shore and Moriches Bay. For those drawn to waterfront living, The Waterways is a new construction gated 55+ community along the shores of Moriches Bay, offering a rare chance to own a home in one of the region’s most sought-after coastal enclaves, with the location, the homes, the amenities, and the site plan of a thoughtfully designed community without the upkeep of a large estate.
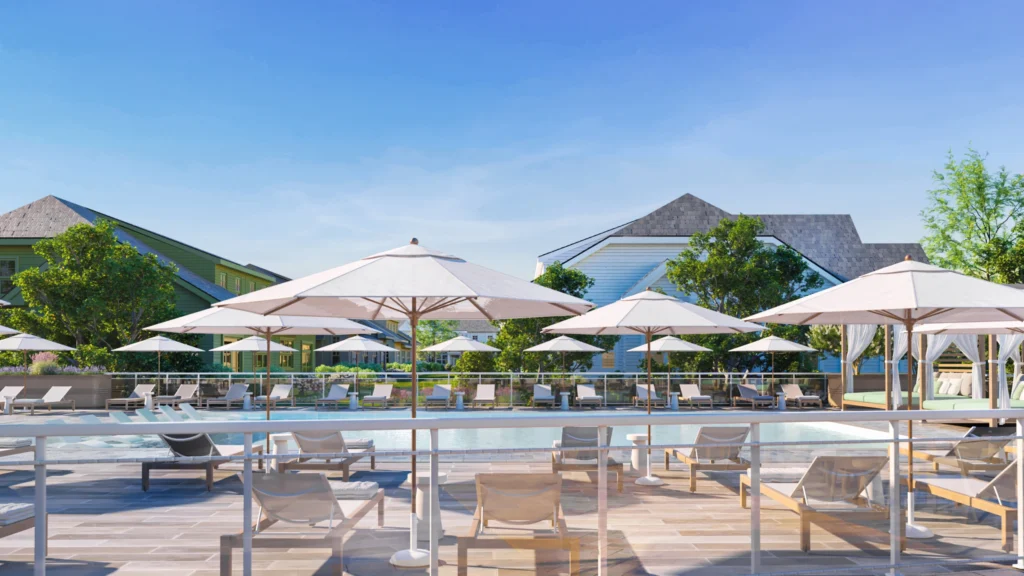
For those who want resort-inspired living with easy access to everyday life, Country Pointe Preserve in Yaphank offers townhomes and villas near LIE Exit 68 with proximity to the Hamptons beaches, the North Shore wine trail, and a full range of amenities, shops, restaurants, and walking trails. Both communities represent what the right downsize home after retirement can look like on Long Island: not less, just better suited to where you are now. If one of them sounds like the right fit, get in touch with The Waterways team or reach out to Country Pointe Preserve to learn more and schedule a visit.